

Marketing · Agencies · Creative studiosMarketing · Agencies
Accountant for marketing agencies with clients abroad
If your agency or creative studio invoices clients abroad and you are thinking of settling in Uruguay, we review your invoicing and structure with you before you take the step. We handle the Uruguayan side; your adviser at home handles your country.
Agencies and creative studios invoicing abroad: invoicing and structure on the Uruguayan side, before you move.
- Since 1993Family accounting firm
- CCEAU 61148 · 225636Registered public accountants
- Written reportConfidential and tailored
- La Barra and remoteServing all of Uruguay
Your situation
What kind of agency are you?
Four common situations. In all of them, the first step is to see what you sell, to whom and from where.
Agency or studio of 2 to 10 people
Performance, content, branding, UX or production, with clients in the United States, Europe or Latin America. We look at it in the diagnostic.
Creative studio
Design, branding, UX or video for agencies and brands abroad, working from briefs. Which part is commissioned work is reviewed against your contracts.
Independent traffic manager or media buyer
You run accounts for brands abroad, on your own or with one or two collaborators. If you work alone, it is looked at differently.
Copywriter, editor or community manager
With regular clients abroad. Each service is analyzed separately.
What changes
Your invoice and your move are two different things.
An agency with clients in the United States and Europe wants to settle in Uruguay. Its first question is whether it will have to add VAT to everything it invoices.
Your invoice
If you are an advertising agency, the client is abroad and the material is used exclusively abroad, the invoice may qualify for export treatment for Uruguayan VAT (IVA), provided all the requirements of the applicable rule are met. Decree 220/998 (art. 34, item 25) provides for this and refers to advertising agencies. If you are a creative studio, media buyer or copywriter, the classification is reviewed separately. We review the service and its supporting documentation before you move.
Your move and your country
Opening a company in Uruguay does not tell you which taxes apply to you in another country. A possible move requires a separate analysis of your tax residency and of the activity carried out in Uruguay. Income tax does not disappear: the activity you carry out from Uruguay is analyzed in Uruguay. Your adviser at home confirms what applies in your country.
We advise only on Uruguay and coordinate with your adviser at home.
What we look at
Three things shape almost everything.
This is what we review in the diagnostic before recommending a structure. How it applies to your case we work out with your data.
Your contracts and briefs
What service you actually provide, to whom and on what terms, as your documents state it.
Where what you produce is used
For export treatment under the advertising-services rule, the material must be used exclusively abroad and all the requirements of article 34, item 25, of Decree 220/998 must be met. We review the supporting evidence.
Your clients’ ad spend
Whether the ad spend goes through your account or straight through the client’s is a question best settled before invoicing.

How we work
From the diagnostic to monthly bookkeeping, with the same firm.
The diagnostic is a written, confidential report.We deliver it within 3 to 5 business days of receiving your complete information and go through it with you in writing, or in a call if you prefer. Scope and fee are agreed before we start. If your case is not a fit, we tell you.
-
Written diagnostic
We look at your activity, your clients and your personal situation, and tell you what needs analyzing and which structure makes sense.
-
Setup
If appropriate, we handle the registration or formation of the company you choose. A sole proprietorship is filed the same day with your complete information; approval depends on DGI and BPS. An SAS is formed with the firm’s own notary public. Invoicing requirements are assessed separately.
-
Monthly bookkeeping
Invoicing and monthly obligations, with one point of contact. From there, we stay with you.
Frequently asked questions
What people ask most before moving an agency
Does my agency pay no VAT if it invoices clients abroad?
It can fall outside Uruguayan VAT if the service is advertising, it is provided by an advertising agency to a client abroad and the material is used exclusively abroad (Decree 220/998, art. 34, item 25). Having a client abroad is not enough on its own: if you are a creative studio, media buyer or copywriter, the classification is analyzed separately. It is confirmed case by case and documented.
What about income tax?
Income tax must be assessed separately. Income from activities carried out in Uruguay is generally Uruguayan-source income; the applicable tax and any amount payable depend on your circumstances and the relevant regime. A move to Uruguay is not presented as a way of avoiding tax.
I still live in another country. Is it worth opening something here?
We can analyze what the company involves on the Uruguayan side. The tax effects in the country where you live are confirmed by your adviser there. A move requires reviewing your tax residency; it does not, by itself, bring a tax benefit.
Does the country my clients are in change anything?
On the Uruguayan side we review the service, who contracts it and where it is used. Any taxes or withholdings in the client’s country must be confirmed with a professional who advises on those rules.
I work alone. Is that the same as an agency?
Not necessarily. Working alone does not settle the classification: we review the activity actually provided. Export treatment under article 34, item 25, of Decree 220/998 is subject to all its requirements, including provision by an advertising agency to a client abroad and use of the material exclusively abroad. We assess the activity and its documentation in the diagnostic.
Further reading
Related guides and official sources.
- Setting up a company in UruguaySole proprietorship or SAS: timelines and what each one includes.
- Forming an SASWith the firm’s own notary public and an accountant, in one process.
- Tax residency in UruguayIf the move is real: what being tax resident means.
If your work is consulting · If you buy and sell goods · If you teach or sell courses online · Our accounting firm in Uruguay for agencies set up as companies · See everyone we advise
Official Uruguayan sources
VAT · Advertising services abroad
VAT · Territoriality
Uruguayan-source income
Tax residency of individuals
Who handles your case
Two registered public accountants, one point of contact.
A partner of the firm handles your case, with complete discretion. If a company is needed, the notary public is the firm’s own.
We work mainly in writing, in your language. Write in English: we reply in English and your report is delivered in English. Calls are also possible.
About the firm · How we work → · Our method (in Spanish) · How our content is prepared
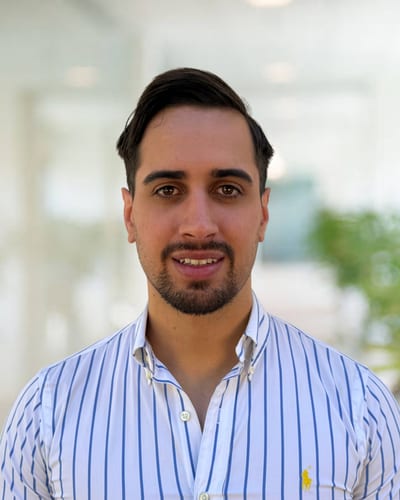
Public Accountant · CCEAU 225636
Handles tax residency, service exports and software cases, including clients based abroad.
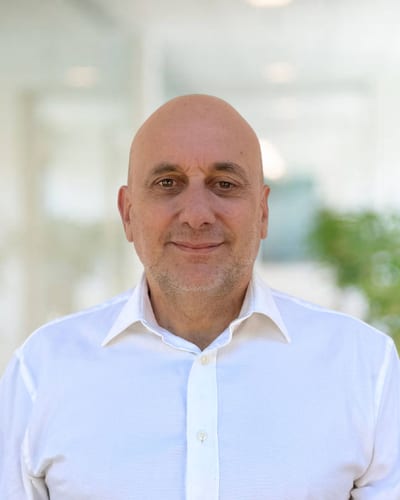
Public Accountant · CCEAU 61148
In practice since 1990; founded the firm in 1993. Companies, tax, payroll and administration.


First step
Tell us about your case and we will tell you what to look at.
Three initial questions: what you sell, where your clients are and when you plan to move. A family firm since 1993, with two registered public accountants and its own notary public. If your case is not a fit, we tell you.
Legal notice: general information on Uruguayan rules in force as of 7 October 2026. It is not advice and does not create a professional relationship: each case depends on its facts, and the rules may change. The examples are illustrative. We deal only with Uruguayan rules. Before making a decision, ask for an analysis of your case. More in the legal notice and scope.