

Uruguayan accountants · In English
Moving to Uruguay and working remotely: how your taxes actually work
Changing country does not mean changing who you work with. What has to be settled first is how your activity is treated once the work is done from Uruguay.
You keep your clients. What changes is how your work is taxed from Uruguay.
- Since 1993Over 30 years in professional practice
- CCEAU 61148 · 225636CCEAU-registered public accountants
- La Barra, MaldonadoOffice visits by appointment
- Anywhere in UruguayRemote service nationwide
In short
Three things to know before you move
-
Where you work from matters more than who pays you.
A foreign client or employer does not, by itself, decide the Uruguayan tax treatment. It is one input into the analysis, not the answer.
-
Employee, contractor or owner: three different cases.
The way you work changes who the taxpayer is, what is being taxed and which rules are even in play.
-
A permit is not a tax status. A company is not a first step.
Immigration status, tax residence and business registration are decided by different rules, at different moments. Residence has its own guide.
Which one are you?
Three ways of working, three different analyses.
Most guides sort people by nationality or by visa. That is not the line that matters. What changes the outcome is how you work.
-
Employee of a company abroad
Your contract stays abroad; the work is now done from Uruguay. A foreign employer does not by itself keep the income outside Uruguay’s reach, and a tax treaty can change the outcome. It is also the profile least likely to need a company.
-
Independent contractor or freelancer
You invoice clients abroad on your own account. Working in your own name and working through a company are both real options, and VAT and social security follow their own logic, which is not the logic of income tax.
-
Owner or founder of a company abroad
Your US LLC, UK company or European entity keeps operating while you live in Uruguay. Four things now have to be looked at together: what you do from Uruguay, what the entity does, your residence position and what your home country still requires.

What people get wrong
“My clients are abroad, so the income is foreign.” Where the money comes from and where the income arises are two different questions.
None of these are exotic.They are the sentences we hear most often in a first conversation, repeated in good faith from something written for a different case.
-
“I invoice a foreign company, so it is an export of services”
Export treatment for VAT applies to defined situations, not to every invoice sent abroad.
-
“A permit for remote workers means I am not taxed here”
An immigration permit governs your right to stay. It is not an exemption.
-
“I will open a company first and sort out the details later”
The structure is the last decision, not the first. Reversing the wrong vehicle costs more than deciding once.
Questions we hear first
Frequently asked questions
I work for a US company. What happens if I move to Uruguay?
The starting point is that the work would then be performed from Uruguay, which calls for its own Uruguayan analysis rather than an assumption that a foreign employer keeps the matter outside the country. What follows depends on your residence position, the terms of your employment and whether a treaty applies between Uruguay and the employer's country. Your US filing obligations are a separate question for a US-qualified adviser.
I am a contractor with clients abroad. Do I need to register in Uruguay?
Carrying out an independent activity from Uruguay generally brings registration obligations with the tax office and the social security institution, and the form that takes depends on the activity and how it is organised. Having only foreign clients does not remove the question, so it is worth confirming before you invoice rather than after.
Can I keep my company abroad?
Owning a foreign entity is not prohibited and we will not tell you to close it. What changes is that your activity in Uruguay, the entity's activity, your residence position and your home country's requirements now have to be looked at together, because decisions in one of them affect the others.
Does being paid from abroad mean the income is foreign-source?
No, not on its own. The location of the person paying you is one fact among several, and it is not the same question as where the income is considered to arise. This is the single most frequent misunderstanding we correct.
Keep reading
What is your next question?
- SAS or sole proprietorshipWhen the question is now which structure to compare.
- Setting up in Uruguay as a foreignerWhen the decision is made and what you need is the order of the steps.
- Software and the tax exemptionWhen the activity is software, where an additional layer of analysis applies.
Moving from the United Kingdom? Read moving to Uruguay from the UK: the tax side before you go.
The full guide
Read the complete analysis
Your situation, why the payer’s country does not decide, the three profiles in detail, the three concepts people merge, what we look at in a review, why talk to us, sources and professional review.
Your situation probably looks something like this
You work in software, consulting, marketing, design, recruitment, IT or another service that travels well, and the people who pay you are in the United States, the United Kingdom, Canada, Europe, Australia or somewhere else outside Uruguay. Moving does not change your work. It changes where the work is performed, and that is the part with consequences.
The questions usually start here: do I need to register anything in Uruguay if all my clients are abroad? Can I keep invoicing the way I do now? Do I need a company, or can I operate in my own name? My employer is abroad, does Uruguay have anything to do with my salary? And then they get harder: does getting a residence permit change my tax position? What happens to the company I already own in my own country? Are there Uruguayan social security contributions in my case? Who tells me what my home country still expects from me?
Most of these questions have an answer. Almost none of them has the same answer for two different people.
Uruguay can be a good outcome. The country that pays you is not what decides it
Uruguay is a serious, stable place to base an international activity, and for some people the result is genuinely attractive. That is a reason to look properly, not a reason to assume. The single most common mistake we see is treating “my clients are abroad” or “I am paid from abroad” as if it were already a tax conclusion.
What actually enters the analysis: where the work is physically performed; what the activity actually is; whether you work as an employee, independently or through an entity; which legal structure, if any, carries the activity; how the service is used by the person paying for it; and your own tax position in Uruguay and elsewhere.
Some services can be treated as exported for Uruguayan VAT purposes, but only where they fall within the situations the regulations actually list and the applicable conditions are met. It is a defined set of cases, not a general principle that applies whenever the client is abroad. So two people receiving the same amount from the same country can end up with different obligations, because the payment is one fact among several and not the conclusion.
The three profiles, in more detail
Profile A, employee of a company abroad. You live in Uruguay, you do the work from Uruguay, and your employment contract stays with a company in another country. Nothing about your job changes. Your payslip still comes from abroad. This is the profile most often misinformed online. A foreign employer does not by itself place the income outside Uruguay’s reach, and employment carried out from Uruguayan territory calls for its own Uruguayan analysis. Whether a tax treaty exists with the employer’s country, and what it says, can change the outcome considerably. It is also the profile least likely to need a company. Opening one because a forum recommended it is how people acquire obligations they did not need.
Profile B, independent contractor or freelancer. You provide services on your own account: consulting, marketing, recruitment, design, software, IT, professional services. Your clients are companies or individuals abroad, and you invoice them. This is the profile where the structure question is genuinely open. Operating in your own name as a sole proprietorship and operating through a company are both real options, and which one fits depends on the activity, how you contract, how you invoice and what you expect over the next few years. It is also the profile where VAT treatment and social security deserve separate attention, because they do not follow the same logic as income tax. One example: if you hold a university degree that qualifies you to practise a regulated profession and you practise it independently in Uruguay, the social security body may be the professionals' fund (CJPPU) rather than the BPS, with its own contribution scale; it is one of the first things we check.
Profile C, owner or founder of a company abroad. You own a US LLC, a UK company, a European entity or another foreign corporation, and it keeps operating while you live in Uruguay. We are not going to tell you to close it, keep it or replace it. That is not a decision anyone can make responsibly from a web page. What we will say is that four things now have to be looked at together: what you personally do from Uruguay, what the foreign entity does, where you stand as a resident, and what your home country still requires. The risk here is rarely a single wrong answer. It is two advisers in two countries each solving half of the problem.
Three things that get treated as one, and are not
A great deal of confusion online comes from three separate concepts being used interchangeably. They are decided by different rules, at different moments, and one does not deliver the others.
Immigration status. Your right to live in the country. A residence permit, or a permit aimed at remote workers, answers whether you may stay. It is not a tax ruling and does not hand you a tax status.
Tax residence. A separate status with its own legal tests, which is why it can arrive earlier or later than you expect, and occasionally without you noticing. It also affects, rather than replaces, what your previous country considers you to be.
Business registration. Whether an independent activity has to be registered with the Uruguayan tax office and the social security institution, and in what form. This is a separate question from immigration status and tax residence.
If the residence side is the part you most need to understand, we cover it properly on its own page: how Uruguayan tax residency works in 2026, including the routes to it and why the headline rate people quote is not automatic.
The assumptions that cause the most expensive corrections
“My clients are abroad, so the income is foreign.” Where the money is paid from and where income is considered to arise are two different questions. Conflating them is the origin of most of the corrections we are asked to make.
“I invoice a foreign company, so it is an export of services.” Export treatment for VAT applies to defined situations that have to be met, not to every invoice sent abroad. The invoice is evidence of a fact, not a category you can elect.
“A permit for remote workers means I am not taxed here.” An immigration permit governs your right to stay. It is not an exemption, and it does not settle the tax analysis on its own.
“I will open a company first and sort out the details later.” The structure is the last decision, not the first. Reversing an entity that turned out to be the wrong vehicle costs considerably more than deciding carefully once.
Why talk to us
We are a family accounting firm in Uruguay, working since 1993, run by Uruguayan public accountants registered with the CCEAU, the national professional body, under registrations 61148 and 225636. Our office is in La Barra, Maldonado, and international cases are handled remotely as a matter of routine.
What that means in practice: you deal directly with the accountants doing the work; the Uruguayan position is explained in English, in writing; we say what is settled and what depends on facts still to be confirmed; and we tell you when the answer is that you do not need what you came to ask for.
We will not describe Uruguay as a zero-tax destination, promise an outcome before seeing the facts, or recommend a structure in a first message. Anyone who does is selling a product rather than looking at your case. If the honest answer is that your situation is simpler than you feared, that is what you will hear.
More questions
Does my tax residence start because I received a residence permit? Immigration status and tax residence are decided by different rules and can begin at different moments. A permit answers whether you may live in the country; it does not by itself determine your tax status.
Can I set up the structure before I move? Sometimes, and there are cases where planning ahead is sensible. What we would not recommend is deciding on the structure before the analysis, because the structure is a consequence of the case rather than a starting point.
What does the review cost? The fee depends on the case. We confirm the scope and the fee in writing before any work begins, so you decide with that information in front of you.
What we look at in a review
The activity you actually perform, not the label on it; where you work from, and how much of the year; who your clients or your employer are, and where; how you are contracted and how you invoice; what already exists (entities, registrations, agreements); the structure options that fit, and the ones that do not; and the points that must be confirmed under your home country’s law. How an engagement works is explained on the expats page.
Sources and scope
Sources and scope. This page reflects the general Uruguayan tax and registration framework as at September 2026, prepared against the applicable legislation and the official guidance of the DGI (the Uruguayan tax office), the BPS (the social security institution), IMPO (the official repository of Uruguayan legislation) and Uruguay XXI (the government investment and export promotion agency). It is informational and does not replace advice on a specific case. The Uruguayan treatment depends on the facts, the activity, where the work is performed, the structure, the documentation and the rules in force at the time of the analysis. Matters governed by another country's law, including your own filing position there, should be confirmed with an adviser qualified in that jurisdiction.
Professional review
- Last reviewed
- 14 September 2026
- Author
- Cr. Matías Zurbriggen, CCEAU 225636 (profile in Spanish)
- Credentials
- The author is a Uruguayan public accountant registered with the CCEAU, the national professional body.
- Related reading in other languages
- Português (same topic, classified by field of work and the Brazilian side) · Español (narrower: the digital nomad permit specifically)
Who analyses your case
Two registered public accountants, one point of contact.
Your case is handled by a partner of the firm, with complete discretion: the report is confidential, and after delivering it we stay with you through implementation.
We work with you mainly in writing, in English, including the report; calls are also possible.
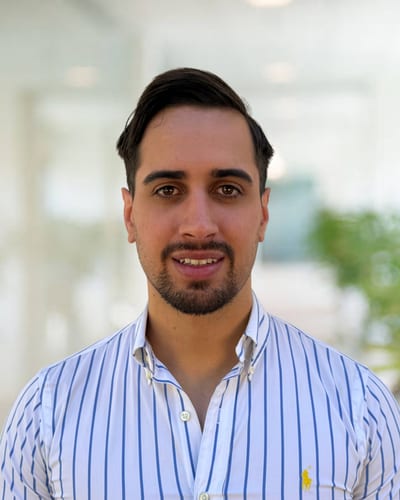
Cr. Matías Zurbriggen
Public Accountant · CCEAU 225636
Handles tax residency, service exports and software, including clients based abroad.
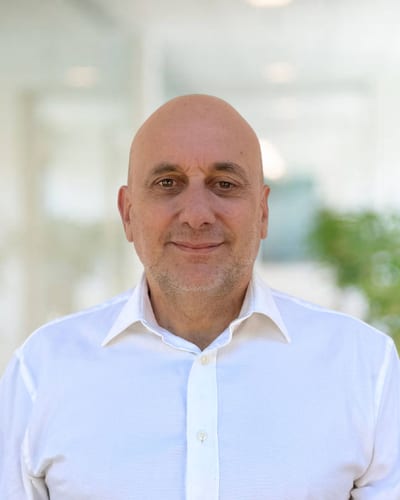
Cr. Fernando Zurbriggen
Public Accountant · CCEAU 61148
In practice since 1990; founded the firm in 1993. Companies, tax, payroll and administration.


Having your case reviewed
Work out where you stand before you set anything up.
Tell us how you work, where you work from and what already exists. You get a professional conclusion on the Uruguayan side of your case and a clear view of the next step, whether or not that step involves us. Scope and fee are confirmed in writing before we start.