

Online teaching and courses · Accountants in UruguayOnline teaching · Uruguay
Accountant for people who teach or sell courses online from Uruguay.
We are accountants in Uruguay for teachers, tutors and course creators who live here or are moving here. We look at three things separately: the VAT on each service, the income tax on your work and the records of your sales and payments.
Accountants in Uruguay: we review the VAT, the income tax on your work here and the records of your payments.
- Since 1993Family accounting firm
- CCEAU 61148 · 225636Registered public accountants
- La Barra + remoteServing all of Uruguay
- Written reportConfidential and tailored
Your situation
You sell knowledge abroad, and VAT is not the only question.
Three typical situations in this field, not client cases.
Recorded course on a platform
A creator sells a course through Hotmart to buyers in several countries and does not know which part of what is paid out to her is her own income.
Review: the diagnostic assesses her income, tax treatment and records before she decides how to invoice.
Live classes by video call
A language teacher gives classes to students in the United States and Europe and is paid through a platform. He does not know how to declare what is paid out to him.
Review: we compare his receipts, tax reporting and supporting records.
Training for companies in other countries
A trainer runs workshops for teams at companies abroad, is paid in dollars and wants to invoice correctly from Uruguay.
Review: we assess the classification of each service and identify questions that still require analysis.
VAT, format by format
Each format is looked at differently.
A sale abroad can only be treated as an export of services if every condition in the rules is met, including that the service is used exclusively abroad. The classification depends on each format and is not promised in advance.
Recorded course, sold to buyers abroad
DGI Tax Consultation Response No. 6508, which is non-binding, treated the on-demand online courses in the case it examined as training and accepted their treatment as an export of services, subject to all the conditions of item 11, including use exclusively abroad. For income tax, it found that this operation combined capital and labor and fell within business income tax (IRAE). Applying it to another case requires reviewing that case’s facts.
Live classes, one-to-one or in groups
The cited consultation responses do not specifically settle live classes, tutoring or language lessons. We review whether the service qualifies as training under article 34, item 11, of Decree 220/998 and whether every export requirement is met, including use exclusively abroad, before defining how to invoice.
Training or workshops for companies abroad
Training is included among the services listed in article 34, item 11, of Decree 220/998. Export treatment requires all the conditions in that provision to be met, including use exclusively abroad. We review the contracted service and the supporting evidence.
Memberships and subscriptions
DGI Tax Consultation Response No. 6000 rejected classification as an export under item 21 for a subscription to informational content not produced at the user’s request. That precedent does not on its own settle the treatment of an educational membership: we review what service the student receives.
Personal coaching and mentoring: an open question; the contract is reviewed. In every format, buyers who live in Uruguay fall outside that logic, and income from work done from Uruguay is declared in Uruguay.

What we look at in your case
Four questions that frame your case.
Your answers tell the diagnostic where to start.What you do not know, we work out together from your sales reports.
-
Where are your students or buyers?
Each one’s country, and whether any live in Uruguay.
-
What exactly do you sell?
Live classes, a recorded course, a membership, mentoring or training.
-
How do you get paid?
A platform, your own website or a bank transfer: each requires different records.
-
Where do you live today?
In Uruguay, about to move, or in another country.
Who it is for
For people who work from Uruguay.
Selling to other countries from Uruguay can be well organized, but it is not a way of not paying tax: income from work done from Uruguay is declared in Uruguay.
If you live in, or are moving to, Uruguay
This is the case we handle: your work is done from here and we organize the Uruguayan side together.
If you still live in another country
Opening a Uruguayan company does not tell you which taxes apply to you in another country. If you plan to move, we analyze your tax residency and the activity on the Uruguayan side. Your adviser at home confirms what applies in your country.
What we cover
Only the Uruguayan side: income tax on work done from Uruguay, VAT, social security, registrations and bookkeeping.
Frequently asked questions
What people ask most before invoicing classes or courses abroad
Do the classes or courses I sell to other countries carry no VAT?
It depends on the service and on whether it meets the conditions for an export of services, including being used exclusively abroad. Consultation Response 6508 analyzes on-demand courses; Consultation Response 6000 deals with a subscription to informational content. Neither automatically determines the treatment of every format. Income tax on the activity carried out from Uruguay is analyzed separately, under the applicable regime.
What about students or buyers who live in Uruguay?
They do not meet the condition of being abroad, so those sales are not treated like the rest. That is why the first step is knowing which countries your students or buyers are in and how many live in Uruguay.
Does what Hotmart, Preply, italki or Udemy pay me already have the taxes sorted out?
Not necessarily. A platform paying money into your account does not on its own determine how you must invoice or declare in Uruguay. We review the sales, fees, withholdings and receipts to establish what applies in your case.
If my students are in other countries, do I still declare income in Uruguay?
Income from an activity carried out in Uruguay is Uruguayan-source income, even if your students or buyers live in another country: the DGI has said so for income from non-resident clients for activities carried out entirely in the country. How much is paid, and how, depends on the way you work and on your situation.
If I still live in another country, is it worth opening a company in Uruguay?
Opening a Uruguayan company does not tell you which taxes apply to you in another country. If you plan to move, we analyze your tax residency and the activity on the Uruguayan side. Your adviser at home confirms what applies in your country.
How do I start?
With the tax diagnostic: you tell us what you sell, where your students or buyers are, how you get paid and where you live, and we send you a written, confidential report within 3 to 5 business days of receiving your complete information. If your income is small, a simpler approach may be appropriate; we assess this with your facts.
Keep reading
Related guides and official sources.
- Calculator for people invoicing abroadAn indicative estimate, based on how you work.
- Software and service exportsClassification, requirements and use exclusively abroad.
- Setting up a company in UruguaySole proprietorship or SAS: timelines and what is included.
- Tax residency and the tax holidayIf you move: what changes with residency.
If you provide training or coaching to companies · If you buy and sell goods · If you teach through a company: our accounting firm in Uruguay · See everyone we advise
Official Uruguayan sources
VAT · Export of services
DGI · On-demand online courses
DGI · Content subscriptions and Uruguayan-source income
Uruguayan-source income
Who handles your case
Two registered public accountants, one point of contact.
A partner of the firm handles your case, with complete discretion. If a company is needed, the notary public is the firm’s own.
We work mainly in writing, in your language. Write in English: we reply in English and your report is delivered in English. Calls are also possible.
About the firm · How we work → · Our method (in Spanish) · How our content is prepared
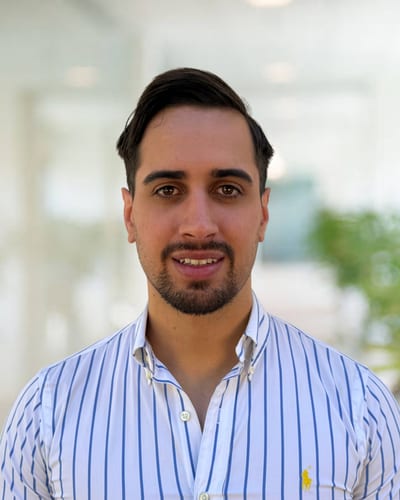
Public Accountant · CCEAU 225636
Handles tax residency, service exports and software cases, including clients based abroad.
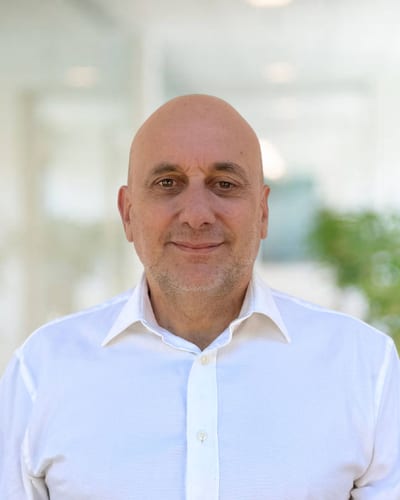
Public Accountant · CCEAU 61148
In practice since 1990; founded the firm in 1993. Companies, tax, payroll and administration.


First step
Tell us what you sell and where your students are, and we look at it with your data.
The tax diagnostic is a written, confidential report on your case. You start with three questions: what you sell, where your students or buyers are and where you live.
Or, if you prefer, message us on WhatsApp.
Legal notice: general information on Uruguayan rules in force as of 7 October 2026. It is not advice and does not create a professional relationship: each case depends on its facts, and the rules may change. The examples are illustrative. We deal only with Uruguayan rules. Before making a decision, ask for an analysis of your case. More in the legal notice and scope.